

The previous post in this two-part series focused on the United State’s current research funding model and the history behind it—but today, we’re facing policy debates that may radically change this long-standing process.
In the last two years, the U.S. federal administration has pushed for changes to how federal funds are allocated and used. A largely impacted area of our current model is indirect costs (IDCs), which have been heavily scrutinized.
Although the proposed 15% flat rate for IDCs failed in 2025, researchers agreed that the way these rates are currently calculated could be made clearer and more transparent.
A coalition of universities and other research institutions created The Joint Associations Group (JAG), and they developed a recommendation known as the Financial Accountability in Research (FAIR) Model—a new way to calculate IDCs.
To recap, indirect costs are expenses of doing research that cannot be directly attributed to a single project. Sometimes referred to as “Facilities and Administration” (F&A), these include electricity, water, research administration, IT services, and other broadly used infrastructural needs. Since it is difficult to set these costs per individual research project, institutions have calculated an average usage cost over a short range of years, approved through a series of negotiations with the federal government (often with accounting offices at the Department of Defense Office of Naval Research and the Department of Health and Human Services).
IDCs vary greatly. For example, Seattle Children’s Hospital’s IDC rate is 87.7% for bench research whereas the University of Mississippi’s IDC rate is 46.5% for on-campus research. And the current process to calculate these rates is long and cumbersome. The FAIR model hopes to change that.
The FAIR model proposes to switch from direct and indirect costs to three new components: Research Performance Costs (RPCs), Essential Research Performance Support (ERPS), and General Research Operations (GROs). RPCs are the same as direct costs—research effort, reagents and supplies, research publication costs, and other expenses that are directly related to the project.
ERPS, the brand new component, takes previous IDC items and reclassifies them as direct costs under four categories.
- Regulatory compliance: Any costs related to human and animal research protections and regulations, like institutional review boards, institutional animal care and use offices, etc.
- Award management, oversight, and reporting: All administrative work highlighted in the research funding roadmap after the notice of award, including financial management of the award, research project progress reporting, and award close-out.
- Research information and data services: Costs of digital repositories where data is stored and/or made accessible for sharing as well as the personnel required to maintain said repositories.
- Essential research performance facilities: Costs for research spaces like utilities and maintenance, leases, and other facility expenses that directly support research.
Although this seems straightforward on paper, the recalculations that institutions would be required to perform may be challenging and cumbersome during the adoption phase. For example, institutional review boards (IRBs) are legally required for any research that involves human subjects; the boards determine whether the research proposal abides by the principles outlined in the Belmont Report to ensure safety of the participants. Currently, when institutions have their own IRBs, the operating costs associated are often characterized as IDCs. In the FAIR model, IRBs would fall under ERPS which means that for each project, there would need to be a budgeted IRB cost—the institution would need to calculate the IRB’s operating costs for the initial application review and for each continuing review or unanticipated problems and adverse events reporting. While initial and continuing reviews may be straightforward to calculate, the operating costs for reporting adverse events and anticipated problems may not be as clear, making calculations challenging in the adoption phase and requiring institutions to do extra work to align their own cost accounting with the new model.
The final component of the FAIR model is GROs—the rest of the indirect costs, which include human resources, procurement, and other resources. The FAIR model recommends that GROs be capped at 15% of the complete research project budget.
Currently, the FAIR model is only a recommendation from JAG and has not been adopted by any funding agency or government office. However, as policy debates on research funding continue, some see it as the best option for research institutions going forward.

Read more in
-

Thank you, GSA community!
Thank you for being a member of the Genetics Society of America! As GSA’s current president, I am writing to tell you about Society projects and initiatives that we hope you will find useful in advancing your science and your career. Scientific research is a collaborative and exciting endeavor. Scientific societies like GSA exist to…
-

Where are they now? Rosalind Franklin Young Investigator Award recipients share updates on their research
Rosalind Franklin Young Investigator Award applications are open–make sure you submit your application or nomination of a colleague by September 30, 2024.
-

University of Minnesota researchers map genome of the last living wild horse species
The study, published in G3: Genes|Genomes|Genetics, is part of larger conservation efforts to save Przewalski’s horse.
-

Congratulations to the Spring 2024 DeLill Nasser Awardees!
GSA is pleased to announce the recipients of the DeLill Nasser Award for Professional Development in Genetics for Spring 2024! Given twice a year to graduate students and postdoctoral researchers, DeLill Nasser Awards support attendance at meetings and laboratory courses. The award is named in honor of DeLill Nasser, a long-time GSA supporter and National Science Foundation…
-

Carolyn Damilola: an NFS Rising Scientist on a lifelong quest to learn more
Carolyn Damilola is an NFS Rising Scientist from Nigeria doing respiratory system research and paving the way for scientists from underrepresented communities through mentorship.
-
What does a good microgrant proposal look like?
Members of the Microgrant Review Committee share their tips for a successful proposal.
-

The first piece of the facial recognition puzzle
New research in GENETICS gives a first peek at the molecular pathway involved in recognizing faces.
-

New Senior Editor Amy MacQueen joins GENETICS
A new senior editor is joining GENETICS in the Genome Integrity and Transmission section. We’re excited to welcome Amy MacQueen to the editorial team.
-

Block party on the zebrafish sex chromosome
Research in G3 identifies a gene regulatory block of the zebrafish genome responsible for overseeing the maternal-to-zygotic-transition.
-

Unraveling the mysteries of duckweed: epigenetic insights from Spirodela polyrhiza
Research published in G3 offers insight into the impact of DNA methylation on clonal propagation in asexually reproducing plants.
-

A microbiologist’s quest to understand CRISPR in bacterial self-defense
2024 Genetics Society of America Medal recipient Luciano Marraffini determined how CRISPR-Cas systems destroy genetic targets with precision, paving the way for gene editing technology development.
-
Unlocking mysteries of trait and disease heritability in dogs
2024 Edward Novitski Prize recipient Elaine Ostrander, a pioneer of the domestic dog model, discovered numerous genes affecting dog size, morphology, behavior, and disease susceptibility—many of which have relevance in humans.
-
GSA and collaborators Personal Genetics Education & Dialogue and Reclaiming STEM Institute launch NSF-funded BIO-LEAPS project to support culture change in genetics
We are thrilled to announce that the Genetics Society of America (GSA) is collaborating with the Personal Genetics Education & Dialogue (PGED) based in the Department of Genetics at Harvard Medical School, and the Reclaiming STEM Institute (RSI) on a Leading Culture Change Through Professional Societies of Biology (BIO-LEAPS) grant from the U.S. National Science…
-

Daman Saluja: Navigating Science and Policy in India
In the Paths to Science Policy series, we talk to individuals who have a passion for science policy and are active in advocacy through their various roles and careers. The series aims to inform and guide early career scientists interested in science policy. This series is brought to you by the GSA Early Career Scientist…
-
A fly geneticist’s journey into discovering rules of organ development
2024 George W. Beadle Award recipient Deborah Andrew discovered new genes and pathways in Drosophila salivary gland organogenesis. Now, her work can help optimize cell secretion in therapeutic applications and fight malaria.
-
Małgorzata Gazda: How receiving the DeLill Nasser Award helped her land her dream job
Have you ever experienced an event that changes the course of your life, or in this case, your career? Małgorzata (Gosia) Gazda is Assistant Professor at the University of Montreal and in 2022, she received the DeLill Nasser Award for Professional Development in Genetics, which she used to attend and present at the 2022 Population,…
-
Hongyu Zhao joins GENETICS as new Senior Editor
A new senior editor is joining GENETICS in the Statistical Genetics and Genomics section. We’re excited to welcome Hongyu Zhao to the editorial team.
-
GSA Member Julio Molina Pineda Receives DeLill Nasser Award, Shines at TAGC 2024
“At any career stage, the GSA membership is an amazing investment for any genetics professional!” Julio Molina Pineda is a PhD Candidate in Cell and Molecular Biology and a Research Assistant at the University of Arkansas, and a Doctoral Academy Fellow at the Lewis Lab. In 2023, Julio was awarded the DeLill Nasser Award for…
-
In Memoriam: Ellsworth Herman Grell (1932–2023), a pioneer of Drosophila genome engineering and annotation
Ellsworth (Ed) Grell blessed the Drosophila community through three enduring legacies: as a pioneer of chromosome mechanics, as a primary organizer and synthesizer of genetic knowledge in Drosophila, and as a graceful mentor to those fortunate to have known him personally. Ed grew up in rural Nebraska, completed his undergraduate studies at Iowa State, and…
-
Congratulations to the #Fungal24 Poster Award winners!
We are pleased to announce the recipients of the GSA Poster Awards for posters presented at the 32nd Fungal Genetics Conference! Undergraduate and graduate student members of GSA were eligible for the awards, and a hard-working team of judges made the determinations. Congratulations to all! Felicia Ebot Ojong, The University of Georgia My research is focused…
-
Poster presentation tips for TAGC 2024
You’ve been selected to present a poster at The Allied Genetics Conference 2024 in March—you’ve celebrated, made plans to attend, now what? This is an exciting opportunity to showcase your research and engage with fellow members of the genetics community, so you want to make sure you’re prepared. We wanted to offer you some tips…
-
Maximize your TAGC 2024 experience
A guide to all that National Harbor & DC have to offer Are you joining us for The Allied Genetics Conference 2024 in March? Make the most of your #TAGC24 experience in National Harbor! We know the science will keep you busy, but you deserve to unwind and have some fun, so we’ve curated a…
-
Early Career Leadership Spotlight: Sarah Petrosky
We’re taking time to get to know the members of the GSA’s Early Career Scientist Committees. Join us to learn more about our early career scientist advocates. Sarah PetroskyMultimedia SubcommitteeUniversity of Pittsburgh Research Interest I am interested in understanding adaptation that has been happening recently in populations by dissecting the ways that genes underlying an adaptation…
-
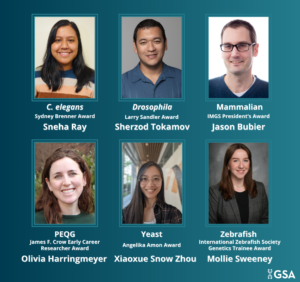
TAGC 2024 Early Career Award Winners
GSA is pleased to announce the winners of the early career awards presented at The Allied Genetics Conference 2024. These awards are specific to particular TAGC communities and recognize early career scientists’ outstanding work on their respective research organisms. The awardees will present their talks in keynote sessions at TAGC 2024. Don’t miss the opportunity…
-
Preeminent geneticists recognized with revamped GSA Awards
In 2022, GSA’s Board of Directors launched an audit to review the five major awards conferred by the Society. Today, we are thrilled to announce the recipients of the reimagined GSA Awards, including the new Genetics Society of America Early Career Medal. The scientists honored this year are recognized by their peers for their outstanding…
-
Fly Board funds outreach programs to spread the word about Drosophila research
In 2020, the Fly Board voted to use part of its reserve fund to support efforts to increase trainee participation as well as equity and diversity in the Drosophila community. An awards committee decides how the money will be spent each year, and from 2020–2022, the committee posted a very broad call for applications from…
-
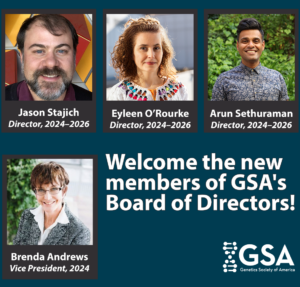
New members of the GSA Board of Directors: 2024–2026
We are pleased to announce the election of four new leaders to the GSA Board of Directors: 2024 Vice President/2025 President Brenda Andrews Professor, University of Toronto It’s an honor to continue my association with the Society by serving as Vice President of the Board of Directors. I have broad knowledge of the ongoing activities…
-

Research funding roadmap: The route to today’s model
Research funding today is complicated. Much of that complexity traces back to World War II, which reshaped who pays for science. Prior to the war, most research funding came from philanthropic donations and government labs. Depending on the donor, funds were used for a new building or to support a specific researcher. For instance, Thomas…
-

Anatomy of an R01 Grant
If you work in a lab that receives funding from the U.S. federal government, chances are that you’ve heard the term “R01” (pronounced “R – OH – 1”). An R01 is one of the many grant types awarded by the National Institutes of Health (NIH). The R series, or Research Grant, is the most common…
-

Genetic model turns routine mating into a visible injury model
A new model of copulatory wounding in Drosophila melanogaster offers a genetic tool to study sexual conflict.